

How to Report a 1031 Exchange – Guide for Tax Filing
A 1031 exchange is generally reported to the IRS using Form 8824, Like-Kind Exchanges, filed with the federal income tax return for the year in which the exchange occurs.
Form 8824 records information about the relinquished and replacement properties, key exchange dates, related-party transactions where applicable, realized and recognized gain, and the basis of the replacement property. (See our guide to where a 1031 exchange is reported on a tax return for a focused breakdown.)
Form 8824 is the core 1031 reporting form, but other forms or schedules can potentially be relevant depending on the transaction and taxpayer.
The purpose of Form 8824 goes beyond simply telling the IRS that a like-kind exchange occurred.
The form documents whether the transaction meets the basic reporting requirements of Section 1031 and performs calculations that can determine how much gain is deferred, how much must be recognized in the current tax year, and the tax basis carried into the replacement property.
- 1. A qualifying 1031 exchange is generally reported on IRS Form 8824, Like-Kind Exchanges.
- 2. Form 8824 is filed with the federal income tax return for the year in which the relinquished property is transferred.
- 3. The form records the properties involved, important exchange dates, related-party information where applicable, realized and recognized gain, and replacement-property basis.
- 4. Realized gain and recognized gain are not necessarily the same amount in a qualifying 1031 exchange.
- 5. Cash, debt relief or other non-like-kind property received can result in some gain being recognized currently.
- 6. Related-party exchanges can create additional reporting obligations.
- 7. Form 8824 is the main exchange-reporting form, but other tax forms or schedules may also be relevant depending on the facts of the transaction.
A 1031 exchange of qualifying real property is generally reported using IRS Form 8824, Like-Kind Exchanges.
For exchanges taking place after the changes introduced by the Tax Cuts and Jobs Act, Section 1031 generally applies only to qualifying real property held for investment or use in a trade or business. Personal property no longer qualifies for Section 1031 treatment.
Form 8824 is normally filed with the taxpayer’s federal income tax return for the year in which the relinquished property was transferred.
In other words, if you transfer your relinquished property during a particular tax year, the exchange is reported with the return for that year, even if a deferred exchange is not completed until early in the following calendar year.
The form does considerably more than record that a taxpayer completed a 1031 exchange.
Parts I through III are used to report the transaction, determine the amount of gain deferred under Section 1031, calculate any gain that must currently be recognized where cash or other non-like-kind property is involved, and establish the basis of the like-kind replacement property received.
Related-party exchanges can create further requirements. The IRS instructions state that Form 8824 needs to be filed for the 2 years following the year of a related party exchange, reflecting the special holding-period and disposition rules that apply to those transactions.
What Information Do You Need to Report a 1031 Exchange?
Completing Form 8824 accurately depends heavily on the records created during the exchange.
You will generally need information covering the properties, dates, values, liabilities and financial components of the transaction.
| Information | Examples |
|---|---|
| Property information | Description of the relinquished and replacement real property |
| Dates | Acquisition, transfer, identification and receipt dates |
| Values | Fair market values where required |
| Exchange proceeds | Cash or other property received |
| Liabilities | Relevant liabilities assumed or from which you were relieved |
| Basis | Adjusted basis and applicable adjustments |
| Expenses | Relevant exchange and transaction expenses |
| Related parties | Details where related-party rules apply |
This checklist is intended to help organize your records. It does not replace the instructions accompanying Form 8824, particularly where the transaction involves multiple properties, liabilities, non-like-kind property, depreciation recapture, related parties or other unusual circumstances.
You should also retain the principal documents supporting the exchange, including:
- settlement or closing statements for both properties;
- qualified intermediary records;
- the exchange agreement;
- the written replacement-property identification notice;
- purchase and sale agreements;
- records of exchange expenses;
- loan and liability information; and
- documents establishing the adjusted basis of the relinquished property.
Keeping these records as the exchange progresses is far easier than attempting to reconstruct the transaction months later when the tax return is being prepared.
How Form 8824 Works
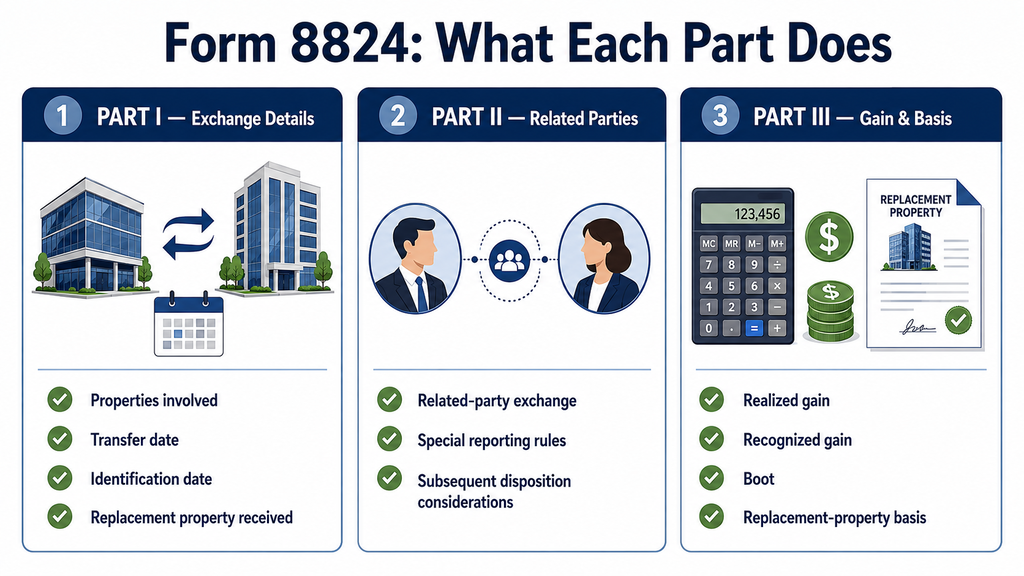
For a conventional Section 1031 exchange, the important reporting work takes place primarily within Parts I, II and III of Form 8824.
Each part performs a different function.
Part I: Information About the Like-Kind Exchange
Part I establishes the basic facts of the exchange.
This includes descriptions of the real properties involved and important dates associated with the transaction.
For a deferred exchange, Form 8824 asks for information such as:
- the property given up;
- the replacement property received;
- when the relinquished property was originally acquired;
- when the relinquished property was transferred;
- when the replacement property was identified; and
- when the replacement property was actually received.
The dates matter because a deferred 1031 exchange is subject to strict identification and completion requirements.
The IRS instructions state that replacement property generally must be identified within 45 days after the relinquished property is transferred and received by the earlier of 180 days after that transfer or the due date of the taxpayer’s return, including extensions.
Form 8824 therefore connects the tax return to what actually happened during the exchange.
From a practical perspective, this is why accurate records need to be maintained while the exchange is taking place. Identification notices, closing documents and QI records establish dates and transaction details that may later be required when Form 8824 is prepared.
Part II: Related-Party Exchanges
Part II deals with exchanges involving related parties.
Section 1031 contains additional rules designed to prevent related taxpayers from using like-kind exchanges in ways that effectively cash one party out while shifting tax basis between related parties.
A related party can include certain family members as well as related corporations, partnerships, trusts, estates and other entities.
The rules can also apply to transactions conducted indirectly through an intermediary. The fact that a qualified intermediary sits between the parties does not necessarily remove the related-party issue.
Subsequent dispositions are particularly important.
Depending on the circumstances, disposing of property received through a related-party exchange within the applicable two-year period can cause previously deferred gain to become reportable. The IRS therefore requires continuing reporting in certain related-party situations following the original exchange year.
Related-party exchanges can become technically complicated quickly. Part II should therefore be viewed as more than a simple question asking whether you know the other party.
Part III: Realized and Recognized Gain
Part III contains much of the financial calculation behind the exchange.
One of the most important concepts to understand is:
Realized gain does not necessarily equal recognized gain. Realized gain reflects the economic gain generated by the transaction.
Recognized gain is the portion that must actually be included for tax purposes in the current year.
A taxpayer could therefore have a substantial realized gain on the disposition of the relinquished property while recognizing only part of that gain, or potentially none of it currently, where the requirements of Section 1031 are satisfied.
For example, assume an investor has an adjusted basis of $300,000 in a property that is transferred as part of a qualifying exchange when its value is $600,000.
Economically, there is a $300,000 gain.
That does not automatically mean the investor reports $300,000 of currently taxable gain. Section 1031 can permit qualifying gain to remain deferred when the investor receives qualifying like-kind replacement real property and the other requirements of the exchange are satisfied.
What Happens if You Receive Cash or Other Non-Like-Kind Property?
The calculation changes when the taxpayer receives money or other property that does not qualify for like-kind treatment.
This is commonly referred to as boot.
The IRS instructions explain that Part III of Form 8824 is used to determine the gain required to be reported currently when cash or non-like-kind property is involved in the exchange.
Boot can include circumstances such as receiving cash from the exchange or receiving other non-like-kind property. Liabilities assumed and liabilities relieved can also affect the exchange calculation.
Receiving boot does not necessarily cause the entire 1031 exchange to fail. Instead, it can cause some of the realized gain to become currently recognized while the remainder continues to qualify for deferral.
For a detailed explanation of how this calculation works, see our guide to how boot is taxed in a 1031 exchange.
Form 8824 and Replacement-Property Basis
Form 8824 also helps determine the taxpayer’s basis in the replacement property.
This is a fundamental part of how 1031 tax deferral works.
The deferred gain has not simply disappeared. Instead, the tax consequences of the exchange are carried forward through the basis of the replacement property.
The IRS instructions state that the amount calculated on Form 8824, line 25, generally represents the taxpayer’s basis in the like-kind property received.
That basis becomes important when calculating future depreciation, determining gain or loss on a later disposition and evaluating what happens if the replacement property is itself used in another 1031 exchange.
For a detailed explanation of the calculation, see our guide to how to calculate 1031 exchange basis.
When Do You File Form 8824?
Form 8824 is generally filed with the federal income tax return for the tax year in which the relinquished property was transferred.
For example, if an investor transfers the relinquished property in December 2026 and receives the replacement property in January 2027, the exchange relates to the tax year in which the December 2026 transfer occurred.
There is an important practical issue when a deferred exchange crosses calendar years.
The replacement-property period ends on the earlier of:
- the 180th day following the transfer of the relinquished property; or
- the due date, including extensions, of the taxpayer’s return for the tax year in which the relinquished property was transferred.
This means that an investor whose 180-day exchange period extends beyond the normal tax-return filing deadline may need to consider obtaining a filing extension so that filing the return does not prematurely shorten the available exchange period.
What if You Completed More Than One 1031 Exchange?
Taxpayers completing multiple like-kind exchanges during the same year can face additional reporting requirements.
The IRS instructions permit taxpayers in certain circumstances to file a summary Form 8824 and attach a statement containing the information required for the individual exchanges. The summary reports the total recognized gain and total basis of the like-kind properties received.
Where multiple properties, multiple exchanges or non-like-kind assets are involved, the calculations can become considerably more complicated than a straightforward one-property-for-one-property exchange.
Does Form 8824 Determine Where Every Amount Appears on Your Tax Return?
No. Form 8824 is the central reporting form for the exchange itself, but other tax consequences can flow to other forms or schedules.
Depending on the taxpayer and the transaction, recognized amounts may interact with other federal tax forms or schedules.
For example, the IRS instructions specifically contemplate situations in which recognized gain may ultimately be reported through forms such as Schedule D, Form 4797 or Form 6252, depending on the nature of the property and transaction.
That is a separate question from understanding how Form 8824 itself works.
If you’re trying to determine where the exchange appears on your federal tax return and which additional forms or schedules may be involved, see our guide to where to report a 1031 exchange on a tax return.
Do You Need a Tax Professional to File Form 8824?
There is no general rule that every taxpayer completing a 1031 exchange must hire a CPA or tax attorney simply because Form 8824 is required.
However, the consequences of getting the exchange calculations wrong can be significant.
Professional assistance becomes particularly valuable where the exchange involves:
- substantial built-in gain;
- multiple replacement properties;
- cash or other boot;
- significant mortgage changes;
- depreciated commercial property;
- related parties;
- mixed-use property;
- multiple asset classes within the real estate;
- installment-sale issues; or
- a reverse or improvement exchange.
A qualified intermediary facilitates the exchange transaction, but the QI should not automatically be treated as the person responsible for preparing your federal tax return or determining your individual tax liability.
The taxpayer remains responsible for reporting the exchange correctly.
What Other Tax Forms May Be Required for a 1031 Exchange?
Form 8824 is the primary federal form used to report a like-kind exchange, but information from the exchange may also affect other parts of the taxpayer’s return depending on the property, recognized gain and circumstances of the transaction.
There is no single additional set of forms that applies to every 1031 exchange. Which forms are relevant depends on factors such as how the relinquished property was used, whether any gain is currently recognized, the character of that gain and the taxpayer’s overall circumstances.
Form 4797: Sales of Business Property
Form 4797, Sales of Business Property, can become relevant when recognized gain or other reportable amounts relate to property used in a trade or business.
The IRS uses Form 4797 for various sales and exchanges involving business property, including depreciable real property and certain gains or losses arising from its disposition.
That does not mean every taxpayer completing a 1031 exchange must file Form 4797. A fully deferred exchange and a partially taxable exchange can produce very different reporting consequences.
Where some gain is recognized, the character of the property and the nature of that gain determine whether Form 4797 or another part of the return becomes relevant.
Schedule D
Schedule D can potentially become relevant where the transaction produces amounts that are treated as sales or exchanges of capital assets or otherwise require capital-gain reporting.
Again, these forms are not automatically required simply because a taxpayer completed a 1031 exchange. Their relevance depends on the character of the property, any currently recognized gain and the particular circumstances of the transaction.
If you are trying to determine exactly where a 1031 exchange appears on your federal income tax return and which additional forms or schedules may apply, see our guide to where to report a 1031 exchange on a tax return.
Form 6252: Installment Sale Income
Form 6252, Installment Sale Income, can also become relevant where part of the transaction qualifies for reporting under the installment method. The current Form 8824 instructions specifically identify Form 6252 as a potentially applicable form in those circumstances. It is not required for every 1031 exchange. Its use depends on whether the transaction includes installment-sale treatment alongside the like-kind exchange.
State Tax Reporting Can Be Different
Federal Section 1031 treatment does not necessarily mean state reporting will be identical.
States can have their own filing, withholding, gain-recognition or deferred-gain tracking requirements. The treatment can also become more complicated when the relinquished property and replacement property are located in different states.
An exchange that qualifies for federal tax deferral should therefore not automatically be assumed to require no separate consideration on the taxpayer’s state return.
The requirements depend on the jurisdictions involved, so state reporting should be reviewed separately from the federal Form 8824 filing.
Records to Keep After a 1031 Exchange
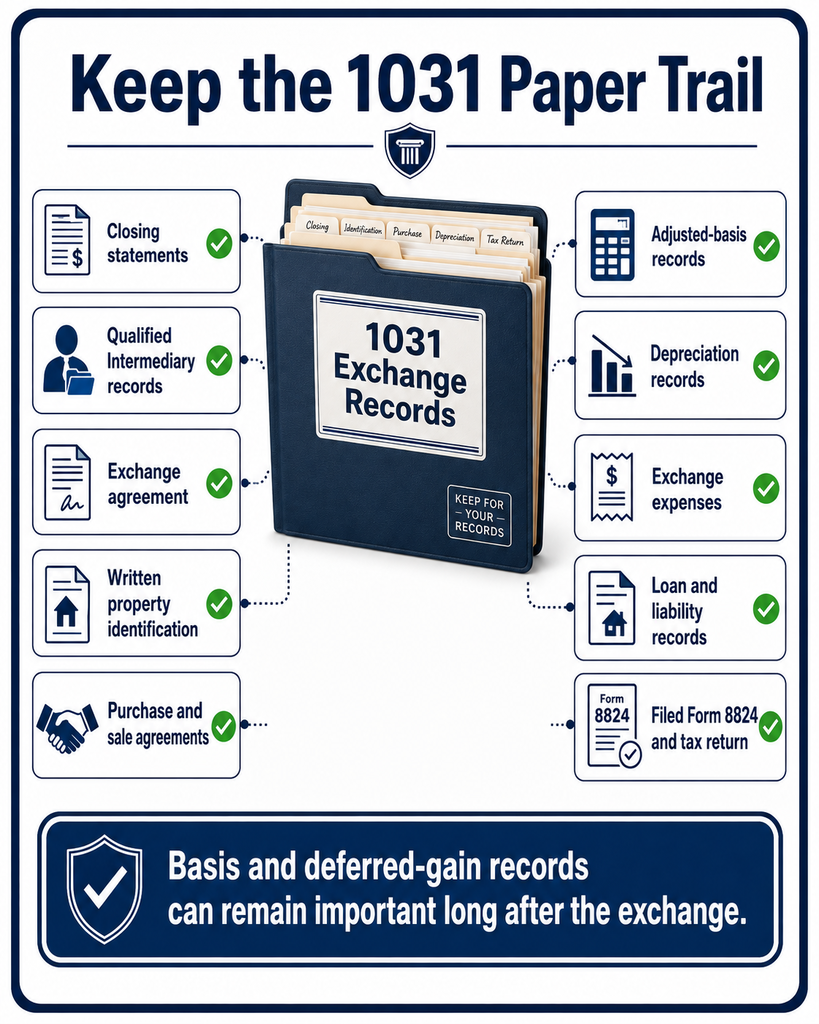
Good recordkeeping is important both when preparing Form 8824 and long after the exchange has been completed.
At a minimum, consider retaining the following records:
| Record | Why It Matters |
|---|---|
| Purchase records for the relinquished property | Help establish the property’s original cost and acquisition history |
| Adjusted-basis and depreciation records | Needed to determine the property’s tax basis immediately before the exchange |
| Relinquished-property sale or closing statement | Documents the transfer price, closing costs, liabilities and other transaction details |
| Exchange agreement | Records the structure and terms under which the 1031 exchange was conducted |
| Qualified Intermediary agreement and statements | Show the QI’s involvement, receipt and movement of exchange funds |
| Written replacement-property identification | Provides evidence of which replacement property or properties were identified |
| Evidence showing when identification was delivered | Helps establish compliance with the applicable identification deadline |
| Replacement-property purchase or closing statement | Documents the acquisition price, liabilities, costs and date the replacement property was received |
| Invoices and evidence for relevant exchange expenses | Support expenses included in the exchange calculations |
| Financing and liability records | Help establish liabilities assumed, paid off or otherwise involved in the transaction |
| Correspondence concerning the exchange | Can provide supporting evidence for dates, instructions and transaction decisions |
| Copy of Form 8824 and the filed tax return | Preserves the reported gain, deferred gain and replacement-property basis calculations |
These records are not useful only for preparing the tax return for the year of the exchange.
Basis and deferred-gain information can remain relevant for as long as the replacement property is held.
The replacement property’s basis can affect future depreciation deductions. If the property is later sold, the basis will affect the calculation of gain or loss. If it is subsequently exchanged again under Section 1031, the existing basis and previously deferred gain can become part of the next exchange’s tax calculations.
Keeping the complete exchange file therefore creates a continuous record of how the tax position attached to the property developed over time.
Common 1031 Exchange Reporting Mistakes
Even where the underlying exchange has been structured correctly, inaccurate reporting or incomplete records can create problems when Form 8824 and the rest of the tax return are prepared.
Using the Wrong Dates
A 1031 exchange can involve numerous dates, including the purchase contract date, closing date, transfer date, identification date and date the replacement property is received.
They are not interchangeable. For reporting purposes, Form 8824 asks for specific dates associated with the acquisition and transfer of the relinquished property and the identification and receipt of the replacement property.
Using a contract-signing date simply because it is easier to find can produce an inaccurate Form 8824 and potentially obscure whether the exchange satisfied the relevant timing requirements.
Losing the Replacement-Property Identification Record
Remembering that a replacement property was identified is not the same as having documentation showing that it was properly identified.
In a deferred exchange, the taxpayer should retain the written identification together with evidence showing when and how it was delivered.
That can include the signed identification notice, acknowledgement from the Qualified Intermediary or other records documenting its timely delivery.
Trying to reconstruct this evidence at tax-filing time is unnecessarily risky.
Treating Realized Gain as Recognized Gain
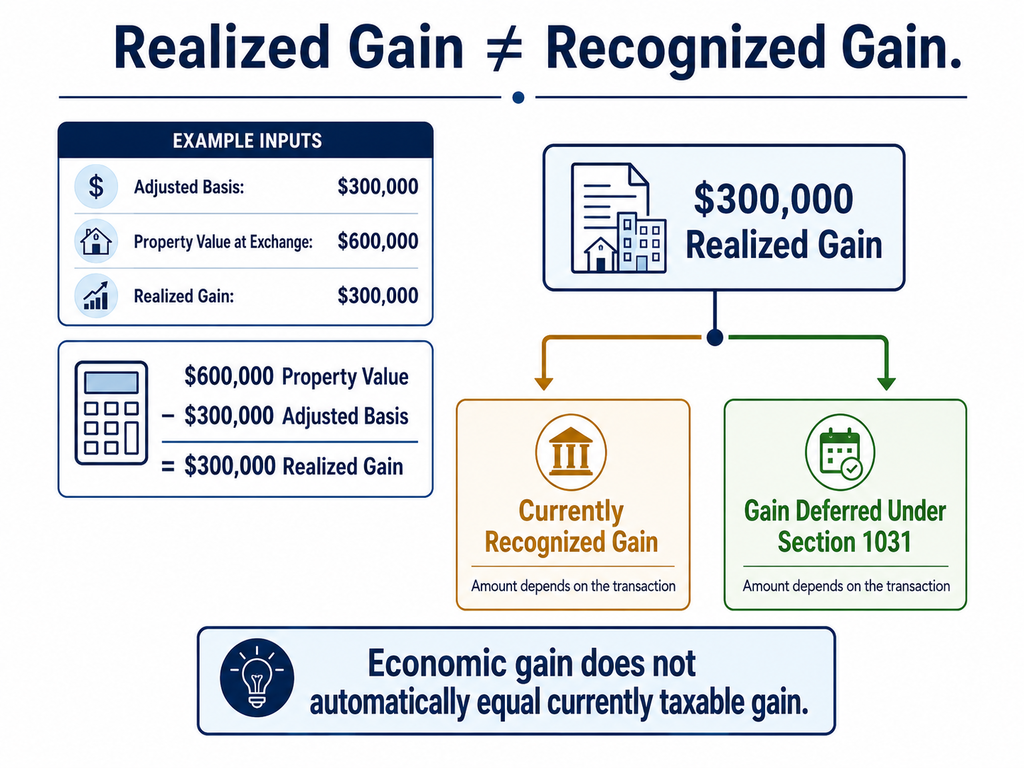
Realized gain and recognized gain are not synonymous in a qualifying 1031 exchange.
Realized gain represents the economic gain generated by the exchange. Recognized gain is the portion that must currently be reported for tax purposes.
Section 1031 can allow some or all of a realized gain to remain deferred.
Automatically treating the entire realized gain as currently taxable would therefore defeat one of the central calculations Form 8824 is designed to perform.
Ignoring Boot
A transaction can qualify as a 1031 exchange while still producing some currently recognized gain.
Cash received, non-like-kind property and certain liability mechanics can affect the amount that must be recognized even where the remainder of the exchange qualifies for tax deferral.
Ignoring those amounts because “it was a 1031 exchange” can result in the taxable portion of the transaction being reported incorrectly.
For a deeper explanation, see our guide to how boot is taxed in a 1031 exchange.
Getting the Replacement-Property Basis Wrong
A common conceptual mistake is to assume that the replacement property automatically receives a completely fresh tax basis equal to its purchase price.
That is not generally how a qualifying 1031 exchange works.
The basis calculation is one of the mechanisms through which deferred gain is preserved after the exchange. An incorrect starting basis can therefore distort later depreciation deductions and the gain or loss calculated when the replacement property is eventually sold or exchanged again.
For more detail, see our guide to how to calculate 1031 exchange basis.
Assuming the Qualified Intermediary Prepares the Tax Return
A Qualified Intermediary performs an important role in facilitating a deferred 1031 exchange, including holding exchange proceeds and helping maintain the required exchange structure.
That does not automatically make the QI responsible for preparing the taxpayer’s Form 8824, determining the correct tax basis, calculating recognized gain or completing federal and state tax returns.
The taxpayer still needs to ensure that the transaction is accurately reported.
The records supplied by the QI can be extremely important to that process, but facilitating the exchange and preparing the tax return are separate functions.
Forgetting Related-Party Reporting
Related-party exchanges are subject to additional rules and reporting requirements.
Form 8824 specifically asks whether the exchange was made directly or indirectly with a related party. Certain related-party exchanges can also create continuing Form 8824 reporting obligations for the two years following the year of the original exchange.
A transaction should therefore not be treated as an ordinary unrelated-party exchange simply because a Qualified Intermediary was involved.
Assuming “Tax Deferred” Means “Nothing to Report”
This is one of the most important misunderstandings to avoid.
A fully tax-deferred 1031 exchange still generally needs to be reported. No currently recognized gain does not mean no reporting obligation.
Form 8824 is used not only to calculate currently recognized gain. It also documents the exchange, records relevant dates and properties, calculates the amount of gain being deferred and establishes the basis carried into the replacement property.
The absence of an immediate federal income-tax bill therefore does not eliminate the reporting requirement.
The practical objective for an investor is not to become their own tax preparer. It is to understand the reporting mechanics well enough to maintain the right records, identify potential problems and provide accurate information to the appropriate tax professional when the return is prepared.
Frequently Asked Questions About Reporting a 1031 Exchange
Do I Have to Report a Fully Deferred 1031 Exchange?
Yes. A fully deferred 1031 exchange generally still must be reported on Form 8824. A qualifying 1031 exchange generally still needs to be reported even when none of the gain is currently recognized.
The IRS states that like-kind exchanges should be reported on Form 8824, Like-Kind Exchanges, even when no gain or loss is recognized.
A fully tax-deferred 1031 exchange still generally needs to be reported. No currently recognized gain does not mean no reporting obligation.
Form 8824 records the details of the exchange and determines matters such as deferred gain and the basis of the replacement property.
What Form Do I Use to Report a 1031 Exchange?
The primary federal form to report a 1031 exchange is IRS Form 8824, Like-Kind Exchanges.
Parts I, II and III of Form 8824 are used to report exchanges of qualifying business or investment real property for like-kind real property. The form records the transaction and calculates deferred gain, any gain that must currently be recognized, and the basis of the replacement property.
See the detailed How Form 8824 Works section above for a breakdown of each part.
When Is Form 8824 Filed?
Form 8824 is generally filed with the taxpayer’s federal income tax return for the tax year in which the relinquished property was transferred.
It is therefore not normally treated as a separate return with a universal filing deadline of its own. Its filing is connected to the taxpayer’s return for the relevant tax year.
Related-party exchanges will create additional reporting obligations. The IRS instructions provide for Form 8824 to be filed for the two years following the year of certain related-party exchanges.
What Information Do I Need for Form 8824?
The information required depends on the transaction, but taxpayers will commonly need records covering:
- the relinquished and replacement properties;
- acquisition and transfer dates;
- replacement-property identification and receipt dates;
- fair market values where applicable;
- adjusted basis;
- liabilities involved in the exchange;
- cash or other non-like-kind property received;
- relevant exchange expenses; and
- related-party information where applicable.
Closing statements, Qualified Intermediary records, the exchange agreement and the written replacement-property identification should be retained alongside the financial records used to prepare Form 8824.
Do I Report a 1031 Exchange if I Received Boot?
Yes. Receiving boot does not remove the Form 8824 reporting requirement. Receiving boot does not remove the requirement to report the exchange on Form 8824. Instead, cash or other non-like-kind property received can cause part of the realized gain to become currently recognized.
Form 8824 is used to determine the amount of gain deferred and the amount that must be recognized where money or non-like-kind property is involved.
For the underlying mechanics, see our guide to how boot is taxed in a 1031 exchange.
Does My Qualified Intermediary File Form 8824 for Me?
Do not assume so. A Qualified Intermediary, or QI, facilitates the exchange and can provide important transaction records needed to prepare Form 8824. That role is separate from responsibility for preparing and filing the taxpayer’s federal or state income tax returns.
Unless the QI has been separately engaged and is appropriately qualified to provide tax-return preparation services, its involvement in the exchange should not be treated as confirmation that Form 8824 or any other tax reporting has been completed.
The taxpayer remains responsible for ensuring that the exchange is properly reported.
Where Does a 1031 Exchange Appear on My Tax Return?
Form 8824 is filed with the relevant federal income tax return, but depending on the transaction, recognized gain or other amounts may also affect other forms or schedules.
For the detailed answer to where the exchange appears and which additional forms may apply, see our separate guide to where to report a 1031 exchange on a tax return.
How Long Should I Keep My 1031 Exchange Records?
There is no useful one-size-fits-all answer that can be applied to every taxpayer simply by counting a fixed number of years from the exchange.
The important point is that records establishing basis and deferred gain can remain relevant after the return for the exchange year has been filed.
Those records may be needed when calculating depreciation on the replacement property, completing another 1031 exchange or determining gain or loss when the replacement property is eventually disposed of.
For that reason, the exchange file should be preserved while its basis and deferred-gain information can still affect the taxpayer’s tax position, together with the supporting tax-return records required under the applicable record-retention rules.
Before You File
If you are preparing to report a 1031 exchange, the practical next step is to assemble the exchange file before attempting to complete the tax return.
That means bringing together the closing statements, Qualified Intermediary records, identification documents, basis and depreciation history, financing records, exchange expenses and other information discussed above.
If your immediate question is which forms or schedules the exchange affects on the federal return, start with our guide to where to report a 1031 exchange on a tax return.
Understanding the mechanics helps you identify missing records and spot potential reporting issues. It does not mean every investor should prepare a complex exchange return without professional assistance.
Where boot, depreciation, multiple properties, related parties, unusual financing or other complications are involved, a tax professional experienced with Section 1031 can review the transaction and determine how it should be reported.
Final Thoughts
Reporting a 1031 exchange correctly is about more than entering a transaction on Form 8824.
The form creates the tax record of what happened. It identifies the properties and relevant dates, establishes the amount of gain that is deferred or currently recognized, and carries important basis information into the replacement property.
That is why good reporting begins before the tax return is prepared.
Keep the transaction records. Understand the distinction between realized and recognized gain. Do not ignore boot, basis or related-party issues. Most importantly, do not assume that a tax-deferred exchange has nothing to report.
Tax deferral changes when qualifying gain is recognized. It does not remove the reporting obligation.
Primary Sources
The reporting information in this guide is based primarily on current Internal Revenue Service guidance:
- IRS: Instructions for Form 8824, Like-Kind Exchanges. Detailed instructions covering the purpose of Form 8824, filing requirements, related-party exchanges, recognized gain and replacement-property basis.
- IRS: About Form 8824, Like-Kind Exchanges. IRS overview and access to the current Form 8824 and instructions.
- IRS Publication 544: Sales and Other Dispositions of Assets. IRS guidance covering like-kind exchanges, qualifying property, recognized gain, basis and related reporting considerations.
September 2026 Update

Nathan Tarrant has worked in and around financial services since 1997, first as founder and COO of an FSA-regulated finanival services business, then as a wealth consultant in Geneva, and since 2009 in digital marketing and search strategist for financial services firms, including Capital Square and Clark Energy Fund Management.
He was co-founder and COO of Alphascend Capital, an oil and gas fund sponsor, from 2022 to 2024.
He is the founder of Bright Ground AI Ltd, a search and AI-visibility agency for financial services, and owner and author of altinvestor.net.
You can read his full bio on our about us page